What Is Invoice Factoring For Business?
Invoice factoring, also called accounts receivable financing, involves selling your unpaid invoices to a factoring company. In exchange, you get an upfront cash advance, often between 70% and 90% of the invoice value. The factoring company then collects the payment from your customer, deducts their fees, and transfers the remaining amount to you.
This arrangement ensures businesses can maintain healthy cash flow without waiting for customers to pay. Unlike loans, factoring doesn’t add debt to your balance sheet, making it an attractive option for businesses looking for immediate liquidity.
Learn more about how invoice finance can work for you.
How Does Invoice Factoring Work For Business?
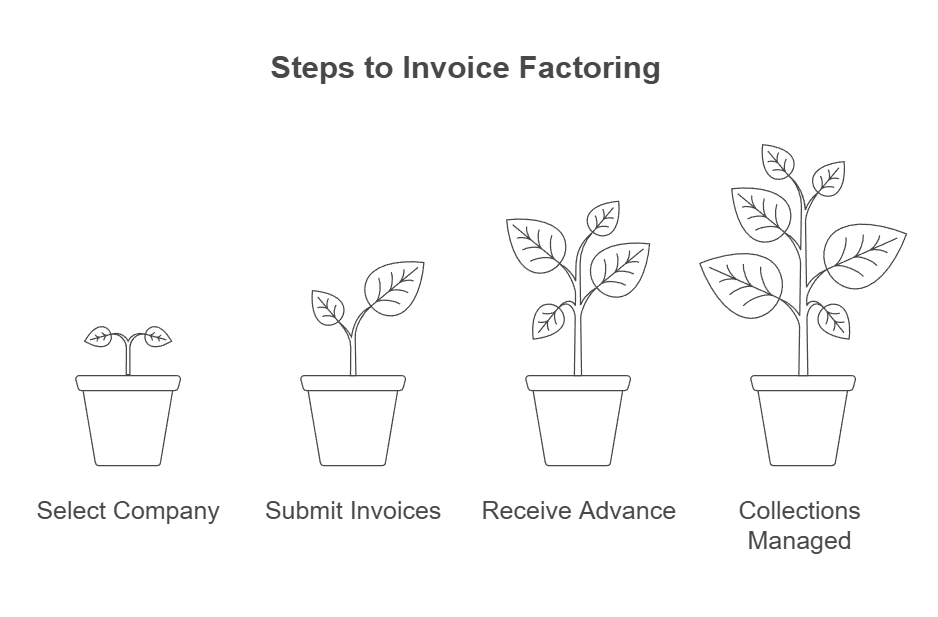
Here’s a step-by-step breakdown:
- Select a Factoring Company: Research providers based on industry expertise, reputation, and customer reviews.
- Submit Your Invoices: Send outstanding invoices to the factoring company for approval.
- Receive an Advance: Once approved, the factoring company pays you a percentage of the invoice value upfront.
- Collections Managed by the Provider: The factoring company takes over the responsibility of collecting payments.
- Final Settlement: After deducting their fees, the company pays you the remaining balance.
Advantages of Invoice Factoring
1. Accelerates Cash Flow
Invoice factoring ensures you’re not stuck waiting for customers to pay, enabling you to:
- Meet payroll deadlines.
- Cover operational costs.
- Invest in growth opportunities.
Example: A manufacturing company in Birmingham used factoring to purchase raw materials quickly, reducing downtime and meeting production targets.
2. Outsourced Invoice Collections
Factoring companies manage the time-consuming task of following up with customers, freeing up your team to focus on core business activities.
3. No Additional Debt
Unlike traditional loans, invoice factoring isn’t considered debt. This means no long-term financial obligations are added to your balance sheet.
4. Accessibility for Small Businesses
Because factoring depends on the creditworthiness of your customers, even businesses with limited credit history can qualify.
5. Scalability
The more invoices you generate, the more funds you can access. This makes factoring a flexible solution that grows with your business.
Explore tailored factoring solutions for your business.
Disadvantages of Invoice Factoring
1. Costs Can Add Up
Factoring fees, including service charges and discount rates, can be higher than traditional financing. This may impact your profit margins over time.
Tip: Carefully evaluate the costs against the benefits to determine whether it’s worth it.
2. Potential Customer Concerns
Some customers might view factoring as a sign of financial instability. Maintaining transparency is essential to preserve trust.
3. Loss of Control
Outsourcing collections means relinquishing some control over how customers are contacted. Choose a factoring provider that aligns with your business values.
4. Not Suitable for Every Business
Factoring companies prioritise the creditworthiness of your customers. If your customer base is deemed risky, you may face challenges securing a factoring agreement.
Factoring is priced on your customers’ reliability, not yours. That is what opens it to young businesses — and what closes it when the ledger looks risky.
Additional Insights: When Is Invoice Factoring Most Useful For Businesses?
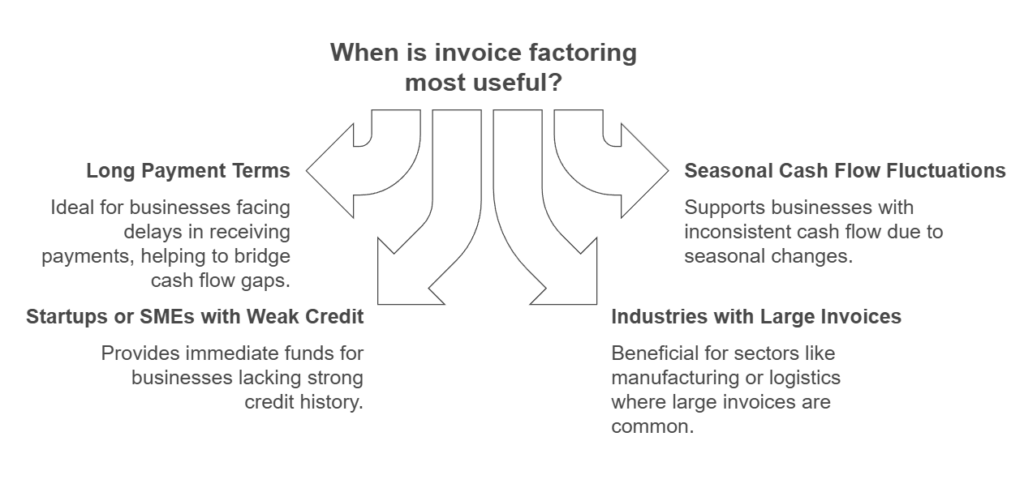
Invoice factoring is ideal for:
- Businesses with long payment terms (e.g., 30-90 days).
- Companies experiencing seasonal cash flow fluctuations.
- Startups or SMEs that need immediate funds but lack strong credit history.
- Industries where large invoices are common, such as manufacturing, logistics, or professional services.
Key Insight: Use factoring as a short-term solution while developing robust credit control systems to reduce reliance on external financing.
FAQs About Invoice Factoring
1. Will my customers know I’m using a factoring company?
Yes, in most cases. The factoring company takes over collections, which means they’ll communicate directly with your customers. Some businesses opt for confidential invoice discounting if they prefer to keep this arrangement private.
Read more about maintaining customer relationships during factoring.
2. How much does invoice factoring cost?
Costs vary but typically include:
- Discount Rate: A percentage of the invoice value (often 1–5%).
- Service Fees: Charges for collections and account management.
Pro Tip: Always request a detailed breakdown of fees before signing an agreement.
Discover how to evaluate factoring costs effectively.
3. What happens if a customer doesn’t pay?
It depends on the type of factoring:
- Recourse Factoring: You’re responsible for unpaid invoices.
- Non-Recourse Factoring: The factoring company absorbs the risk.
Learn about managing non-payment risks.
4. Can I factor all my invoices?
Most factoring companies prefer invoices with well-established, creditworthy customers. Low-value or high-risk invoices may not qualify.
Find out how to select invoices for factoring.
5. Is invoice factoring better than a loan?
It depends on your needs. Factoring provides immediate cash without adding debt, but loans might be cheaper if you have strong credit.
Compare invoice factoring and traditional loans.
Comparing Invoice Factoring with Other Financing Options
If invoice factoring isn’t the best fit, consider these alternatives:
- Traditional Bank Loans: Best for businesses with strong credit and collateral.
- Lines of Credit: Flexible and ideal for bridging short-term cash flow gaps.
- Business Credit Cards: Convenient but often comes with high interest rates.
- Peer-to-Peer Lending: Peer-to-peer platforms connect businesses with individual investors. This option often provides competitive rates, particularly for businesses with unique circumstances.
- Invoice Financing Platforms: These platforms connect businesses with investors willing to purchase invoices at a discount, offering flexibility and often lower costs compared to traditional factoring.
Each financing option comes with its own advantages and drawbacks, so it’s crucial to assess which solution aligns best with your business needs and long-term goals.
Discover alternative financing solutions tailored to your business requirements.
How to Choose the Right Factoring Provider
When selecting a factoring provider, the following considerations can ensure a positive experience:
- Reputation and Experience — Work with providers who specialise in your industry and have a proven track record.
- Transparency in Terms — Request detailed agreements that outline fees, termination clauses, and flexibility in contract terms.
- Customer Service — Choose a provider with strong customer support. A responsive team can make all the difference when addressing queries or resolving issues.
- Scalability — Ensure the factoring company can accommodate your business as it grows, supporting larger funding requirements.
- Added Value — Some providers offer additional services, like credit checks on customers or enhanced reporting tools, to give you greater insight into your financial operations.
Tip: A reliable provider should feel like a partner invested in your success, not just a service provider. Contact Guavas to find out more about the factoring facilities we arrange across our panel of funders.
Conclusion: Is Invoice Factoring Right for You?
Invoice factoring can be a game-changing solution for businesses looking to improve cash flow, minimise collection hassles, and access immediate working capital. However, it’s not a one-size-fits-all approach. Careful consideration of costs, customer relationships, and long-term financial goals is essential.
Key Takeaways:
- Invoice factoring is ideal for businesses needing quick cash flow without taking on additional debt.
- It works best for companies with creditworthy customers and a steady volume of invoices.
- Alternatives like loans, credit lines, or peer-to-peer lending may suit businesses with stable cash flow or strong credit.
Take Action Today — If you’re ready to explore how invoice factoring can transform your cash flow, get your free quote now or read more about invoice finance.