When faced with funding needs for your business, choosing between secured and unsecured loans can significantly impact your company’s financial health and growth trajectory. Imagine you’re running a small manufacturing business in Leeds that needs £75,000 to purchase specialized equipment. You could secure this loan using your existing machinery as collateral and benefit from lower interest rates, or you might opt for an unsecured loan to protect your assets despite higher costs. This decision isn’t just about immediate access to capital—it’s about balancing risk, cost, and your long-term business strategy.
In the UK, business owners frequently navigate this crucial financing decision. Whether you’re expanding operations, managing seasonal cash flow fluctuations, or investing in growth opportunities, understanding the fundamental differences between these loan types is essential for making informed financial choices that align with your business goals.
Secured vs Unsecured Business Loans: Understanding the Differences
Before diving into specific advantages and disadvantages, it’s important to understand what fundamentally separates these two financing options. The primary distinction—collateral—influences everything from approval requirements and interest rates to borrowing limits and repayment terms.
What is a secured business loan?
A secured business loan requires you to pledge specific assets as collateral to guarantee repayment. This collateral serves as security for the lender—if you default on the loan, they have legal rights to seize and sell these assets to recover their funds.
When applying for a secured loan, lenders evaluate both your creditworthiness and the value of your proposed collateral. Common forms of collateral include:
- Commercial or residential property
- Business equipment and machinery
- Vehicles and fleet assets
- Inventory
- Accounts receivable
- Cash savings or investments
For example, a restaurant owner might secure a £200,000 loan against their commercial kitchen equipment and property lease. The collateral reduces the lender’s risk, which typically translates into more favorable terms for you as the borrower.
Secured loans are particularly common for larger funding amounts and longer-term financing needs. Traditional banks are the primary providers of secured business loans in the UK, though alternative lenders increasingly offer these options as well.
Have you considered how your business assets could work harder for you by unlocking their value through secured financing?
Learn more about valuing your business assets for loan applications
What is an unsecured business loan?
An unsecured business loan provides funding without requiring specific assets as collateral. Instead, approval depends primarily on your business’s creditworthiness, financial performance, and future earning potential. Lenders assess risk through your:
- Business and personal credit scores
- Trading history and time in business
- Annual revenue and profitability
- Cash flow stability
- Industry outlook and business model viability
Consider a digital marketing agency seeking £30,000 to hire additional staff and upgrade their software systems. With strong financials but few physical assets, an unsecured loan allows them to obtain necessary funding based on their proven revenue stream rather than collateral.
While unsecured loans don’t put specific assets at risk, they often include personal guarantees from business owners. This means you may still bear personal financial responsibility for repayment, even without pledging specific collateral.
Unsecured loans are particularly valuable for service-based businesses, startups with limited physical assets, and companies needing quick access to smaller funding amounts. They offer flexibility and accessibility that secured loans sometimes cannot match, albeit typically at higher costs.
Find out how bad credit business loans work if your credit history is less than perfect
Key Differences Between Secured and Unsecured Business Loans
Understanding these fundamental differences helps you determine which option best suits your specific business needs:
Collateral Requirement
The most obvious distinction is that secured loans require specific assets as collateral, while unsecured loans don’t. This fundamental difference influences all other aspects of the loan structure and approval process.
Risk Allocation
Secured loans shift a significant portion of risk to you as the borrower, as your pledged assets are at stake if you default. Unsecured loans place more risk on the lender, which explains their higher costs.
Interest Rates
The interest rate difference between secured and unsecured loans can be substantial—typically 3-7% in the UK market. For example, a £100,000 secured loan might come with a 5-6% interest rate, while a similar unsecured loan might charge 9-13%.
This difference translates to significant savings over the life of the loan. On that £100,000 loan with a 5-year term, you might save approximately £15,000 in total interest with a secured versus unsecured structure, assuming a 6% rate difference.
Loan Amounts and Terms
Secured loans typically offer access to larger funding amounts—sometimes reaching into millions of pounds for substantial assets—and longer repayment terms, often extending to 10-25 years for property-secured loans.
Unsecured loans generally cap at lower amounts, typically £25,000-£250,000 depending on the lender and your business’s financial strength. Repayment terms are also shorter, usually ranging from 6 months to 5 years.
Approval Process and Timeline
The approval process for secured loans tends to be more complex and time-consuming, often taking several weeks or even months. Unsecured loans typically feature streamlined approval processes, with some online lenders offering decisions within hours and funding within days.
Would your business benefit more from the lower costs of a secured loan or the speed and simplicity of an unsecured option?
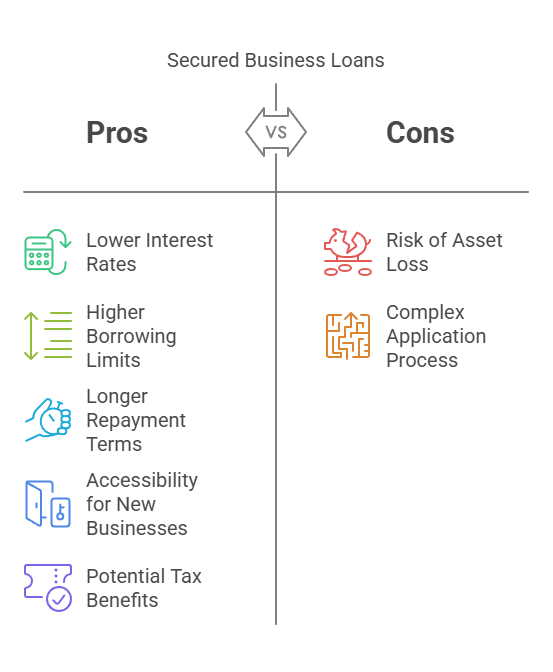
Pros and Cons of Secured Business Loans
Secured business loans offer distinct advantages and disadvantages that make them suitable for specific business situations. Understanding these factors helps you determine whether pledging collateral aligns with your business strategy and risk tolerance.
Benefits of Secured Business Loans
Lower Interest Rates
The most significant advantage of secured loans is their cost-effectiveness. By providing collateral, you substantially reduce the lender’s risk, resulting in interest rates that can be 3-7% lower than unsecured alternatives.
For substantial loan amounts, this difference translates into thousands or even tens of thousands of pounds in savings over the loan term. A manufacturing business securing a £250,000 loan against its equipment might pay 6% interest instead of 12% for an unsecured option, saving approximately £75,000 in interest over a 10-year term.
Higher Borrowing Limits
Secured loans typically allow you to borrow larger amounts, with limits primarily determined by the value of your collateral rather than your business’s current revenue. This increased borrowing capacity enables more substantial investments that might otherwise be impossible to finance.
For businesses planning major expansions, property acquisitions, or equipment purchases, secured loans may be the only viable option to access sufficient funding. Some UK lenders offer secured loans reaching into millions of pounds for businesses with valuable collateral, far exceeding typical unsecured loan limits.
Longer Repayment Terms
The extended repayment periods available with secured loans—often ranging from 5 to 25 years—result in lower monthly payments that are easier to manage within your cash flow. This extended amortization is particularly valuable for capital-intensive investments that generate returns over many years.
For example, a commercial property purchase financed through a 20-year secured loan allows you to match loan repayments with the long-term income generated by the property, creating a sustainable financial structure that preserves working capital.
Accessibility for Businesses with Limited Credit History
Secured loans can provide access to funding for businesses that might not qualify for unsecured options due to limited trading history or less-than-perfect credit scores. The collateral reduces the lender’s reliance on credit history as the primary risk indicator.
This accessibility is particularly valuable for younger businesses that have accumulated assets but haven’t yet established extensive credit histories. It creates financing opportunities that would otherwise be unavailable through conventional unsecured channels.
Potential Tax Benefits
Interest payments on business loans are generally tax-deductible as business expenses in the UK, and secured loans often involve larger amounts with longer terms, potentially increasing these deductions. Additionally, certain secured loans used for specific purposes like equipment purchases may qualify for additional tax advantages.
Compare the different business financing options available
Cons of Secured Business Loans
Risk of Asset Loss
The most significant drawback of secured loans is the potential loss of pledged assets if your business encounters financial difficulties. This risk is particularly concerning when the collateral includes essential business assets or personal property like your home.
Before proceeding with a secured loan, carefully assess your business’s stability and cash flow projections. Consider whether you could maintain repayments even during temporary downturns or seasonal fluctuations in your business.
Lengthy and Complex Application Process
Secured loans typically involve more extensive documentation and longer approval timelines than unsecured alternatives. The process often includes:
- Professional valuation of collateral assets
- Legal searches and title verification
- More extensive financial documentation
- Longer underwriting procedures
This extended timeline—often 3-8 weeks rather than days—can be problematic when facing time-sensitive opportunities. The additional complexity also increases the administrative burden on your business during the application process.
Upfront Costs and Fees
Securing a loan against property or significant assets typically involves various upfront expenses that can add substantially to the effective cost of borrowing:
- Valuation fees for collateral assessment (£500-£2,000)
- Legal fees for documentation and searches (£1,000-£3,000)
- Arrangement fees (often 1-2% of the loan amount)
- Insurance requirements for pledged assets
These costs can add 2-4% to the total loan expense, representing thousands of pounds for substantial borrowing amounts. While these fees are sometimes rolled into the loan amount, they still increase the overall cost of financing.
Restrictions on Collateral Usage
When you pledge assets as collateral, you may face restrictions on selling, modifying, or further leveraging these assets during the loan term. These limitations can constrain your business flexibility and complicate future strategic decisions.
For example, equipment secured against a loan might require lender approval before being upgraded or replaced, potentially hampering your ability to adapt to changing business needs or technological advancements.
Discover strategies for minimizing business loan risks
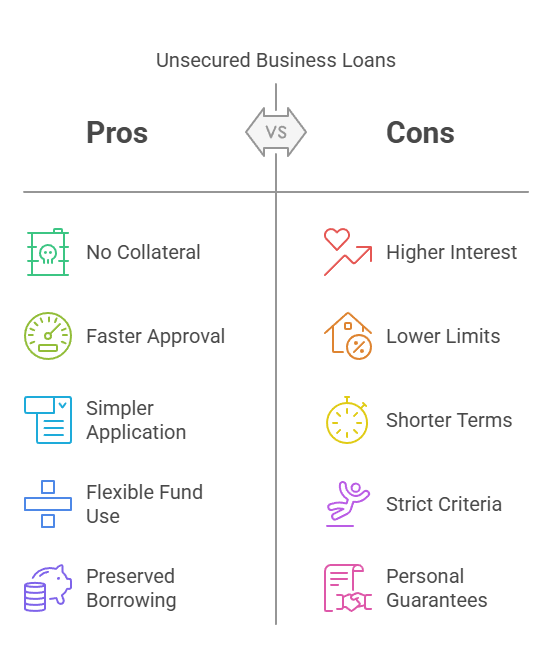
Pros and Cons of Unsecured Business Loans
Unsecured business loans offer a distinct set of advantages and challenges compared to their secured counterparts. Understanding these factors helps you determine whether this financing option aligns with your business needs and risk preferences.
Benefits of Unsecured Business Loans
No Collateral Requirement
The most obvious advantage of unsecured loans is that they don’t require specific assets as security. This benefit is particularly valuable for:
- Service-based businesses with limited physical assets
- Startups and early-stage companies still building their asset base
- Businesses whose assets are already leveraged or unsuitable as collateral
- Owners who prefer not to risk specific business or personal assets
This absence of collateral requirement preserves your flexibility to manage business assets according to operational needs rather than lender requirements. It also protects critical assets from potential seizure if business conditions deteriorate unexpectedly.
Faster Approval and Funding
Unsecured loans typically feature significantly streamlined application processes and quicker funding timelines. Without the need for collateral valuation, legal searches, and extensive documentation, many UK lenders can provide decisions within 24-48 hours and funding within 2-5 business days.
This speed can be crucial when responding to time-sensitive opportunities or challenges:
- Taking advantage of limited-time supplier discounts
- Addressing unexpected equipment failures
- Capitalizing on seasonal inventory opportunities
- Managing temporary cash flow gaps
For a retail business needing to quickly stock up before the Christmas selling season, an unsecured loan might deliver funding in 3-5 days, compared to several weeks for a secured option—a difference that could significantly impact sales potential.
Simpler Application Process
Unsecured loan applications generally require less documentation and administrative effort than secured alternatives. The focus shifts from collateral assessment to financial performance metrics, streamlining the process for both borrowers and lenders.
Typical documentation for unsecured loans includes:
- 3-6 months of business bank statements
- Basic financial statements
- VAT returns (if applicable)
- Business identification documents
This simplified process reduces the administrative burden on your business and minimizes the opportunity cost of pursuing financing.
Flexibility in Fund Usage
Unsecured loans typically offer greater flexibility in how you utilize the funds. While secured loans are often tied to specific purposes related to the collateral (like property purchase or equipment financing), unsecured loans can generally be used for any legitimate business purpose.
This flexibility allows you to allocate funds according to evolving business needs rather than predetermined categories. Whether you’re investing in marketing, hiring staff, developing new products, or managing working capital, unsecured loans provide the adaptability to support various aspects of your business strategy.
Preserved Borrowing Capacity
By obtaining financing without pledging assets, you preserve your ability to use those assets as collateral for future borrowing needs. This maintained borrowing capacity creates strategic flexibility for longer-term planning and future growth opportunities.
For businesses anticipating multiple funding needs over time, starting with unsecured options for smaller or shorter-term requirements can preserve secured borrowing capacity for major investments that truly require it.
Explore alternative financing options for UK small businesses
Cons of Unsecured Business Loans
Higher Interest Rates
The most significant disadvantage of unsecured loans is their cost. Without collateral to reduce lender risk, interest rates typically range 3-10% higher than comparable secured options, substantially increasing the total cost of borrowing.
For example, a £50,000 unsecured loan at 12% interest over 3 years would cost approximately £9,500 in total interest, compared to about £4,000 for a secured loan at 5% interest—a £5,500 difference that directly impacts your bottom line.
Lower Borrowing Limits
Unsecured loans generally offer smaller maximum amounts than secured alternatives. While specific limits vary by lender and your business’s financial strength, unsecured loans typically cap at £25,000-£250,000 in the UK market, with amounts above £100,000 requiring exceptional business performance.
These limitations can be problematic for capital-intensive projects or major expansions that require substantial funding. Businesses needing larger amounts often find themselves piecing together multiple financing sources or ultimately turning to secured options.
Shorter Repayment Terms
Unsecured loans typically feature compressed repayment schedules, usually ranging from 3 months to 5 years, with most falling in the 1-3 year range. These shorter terms result in higher monthly payments that can strain cash flow, particularly for businesses with seasonal or variable revenue patterns.
A £100,000 loan repaid over 2 years requires monthly payments approximately 2.5 times higher than the same amount amortized over 5 years. This accelerated repayment schedule demands careful cash flow planning to ensure sustainability.
Stricter Eligibility Requirements
Without collateral to mitigate risk, lenders impose more stringent qualification criteria for unsecured loans. These typically include:
- Stronger credit scores (often 650+ for competitive rates)
- Longer trading history (usually minimum 1-2 years)
- Higher revenue thresholds
- Proven profitability
- Clean credit history with no significant adverse events
These requirements can exclude many newer businesses or those with past financial challenges, limiting accessibility compared to secured options that place greater emphasis on collateral value.
Personal Guarantees
While unsecured loans don’t require business assets as collateral, most lenders still require personal guarantees from directors or owners. These guarantees make you personally liable for repayment if your business defaults, potentially putting your personal assets at risk despite the “unsecured” classification.
Choosing the Right Loan for Your Small Business
Selecting the right loan type depends on your unique business circumstances, financial position, and strategic objectives. Consider these key factors when making your decision:
Are there any collateral requirements?
The first question to ask yourself is whether you have valuable assets available—and are willing—to pledge as collateral. Consider:
- What business or personal assets could serve as collateral?
- What is the approximate value of these assets relative to your funding needs?
- How essential are these assets to your ongoing business operations?
- Would you be comfortable with the risk of losing these assets if repayment becomes challenging?
If you have substantial unencumbered assets and are comfortable with the associated risks, a secured loan might be appropriate. For a manufacturing business with £500,000 in equipment and a need for £200,000 in financing, using that equipment as collateral could unlock favorable loan terms while keeping monthly payments manageable.
Conversely, if you lack significant assets or prefer not to risk them, an unsecured loan may be your only viable option. Service businesses like consultancies or digital agencies often fall into this category, with their primary assets being intellectual property and human capital rather than physical equipment.
See how lenders value business assets as security
Are there any risks, credit impact and Interest Rates
Every financing decision involves balancing risk against reward. With secured loans, the primary risk is losing pledged collateral if your business encounters difficulties. With unsecured loans, the risks include higher costs and potential personal liability through guarantees.
Consider how different loan structures might impact your credit profile:
- Both loan types can positively impact your business credit score when managed responsibly
- Secured loans may offer more flexibility during temporary financial challenges
- Defaults on either loan type can severely damage both business and personal credit
- Multiple unsecured loans can create a higher debt service burden that may affect future borrowing capacity
Interest rates represent the most significant cost difference between these loan types. In the current UK market:
- Secured business loans typically range from 3-8% depending on collateral quality and loan-to-value ratio
- Unsecured business loans generally range from 7-25% based on business strength, credit history, and loan term
This difference becomes more pronounced with larger loan amounts and longer terms. For a £150,000 loan over 5 years, the difference between a 5% secured rate and a 12% unsecured rate amounts to approximately £30,000 in additional interest—a substantial impact on your business’s financial performance.
How would these different interest scenarios affect your cash flow and profitability projections?
Learn how Guavas arranges business loans across a panel of funders
Loan Amount and Terms
Your funding requirements and repayment capacity should significantly influence your loan choice:
Loan Amount
If you need a substantial sum—particularly over £250,000—secured loans will typically offer more options. The maximum amount available through secured financing is primarily limited by your collateral value rather than your current business revenue.
For smaller amounts under £50,000, unsecured loans often provide sufficient funding with less complexity and faster access. Many UK online lenders specialize in these smaller unsecured facilities with streamlined application processes.
Repayment Terms
Consider how loan repayments will fit into your cash flow:
- Secured loans offer longer terms (5-25 years), resulting in lower monthly payments
- Unsecured loans typically require repayment within 1-5 years, creating higher monthly obligations
- Seasonal businesses may benefit from the lower payments of secured loans during off-peak periods
- Growth-focused businesses might prefer the shorter commitment of unsecured loans
For example, a £100,000 loan at 6% interest would require monthly payments of approximately £1,933 over 5 years, compared to £1,110 over 10 years. This difference of £823 per month could be crucial for businesses with tight cash flow margins.
Explore business loan refinancing options
Purpose Alignment
Match your loan structure to your funding purpose:
- Long-term investments (property, major equipment) align better with secured loans
- Short-term needs (inventory, marketing, working capital) may be better served by unsecured options
- Mixed purposes might require a combination of financing types
Approval Process
The timeline for accessing funds can be a decisive factor, particularly when facing time-sensitive opportunities or challenges:
Secured Loans
- Typical approval timeline: 3-8 weeks
- Documentation requirements: Extensive (financial statements, business plans, collateral documentation, legal searches)
- Application complexity: High, often requiring professional assistance
Unsecured Loans
- Typical approval timeline: 1-10 business days
- Documentation requirements: Moderate (recent bank statements, basic financials, identification)
- Application complexity: Low to moderate, often manageable without external support
For businesses needing rapid access to capital, the streamlined process of unsecured loans can be compelling despite higher costs. A retail business needing to quickly secure seasonal inventory might find that an unsecured loan’s faster funding outweighs its higher interest rate, particularly if the inventory generates strong margins.
Conversely, businesses with longer planning horizons might prefer to invest time in the secured loan process to benefit from better terms, especially for substantial amounts or long-term investments.
Compare business loan terms with Guavas Finance
Arrange a Secured or Unsecured Loan with Guavas Finance
At Guavas Finance, we understand that every business has unique funding needs and circumstances. Our experienced team helps UK small businesses navigate the complex landscape of business financing to find the optimal solution.
Whether you’re looking for a secured loan to fund major expansion plans or an unsecured facility to manage working capital, we can:
- Compare secured and unsecured terms across a panel of funders
- Match your business to funders who lend against your asset profile and trading history
- Set out the rates, fees and security each funder will ask for before you commit
- Arrange repayment terms that work with your business cash flow
- Give you personalised service from dedicated finance specialists who understand your industry
Our straightforward application process eliminates unnecessary complexity, and our transparent approach ensures you understand exactly what you’re paying. We work with a diverse panel of funders to match your business with the most suitable financing options based on your specific circumstances and objectives.
Take the first step toward securing the right funding for your business. Get a quote — it takes minutes, there is no obligation, and we will explore how we can support your business growth through tailored financing solutions.
Choosing between secured and unsecured business loans requires careful consideration of several factors. Throughout this article, we have explored the definitions and differences between secured and unsecured business loans, discussed their pros and cons, and provided guidance on determining the most suitable option for your business. Secured loans offer lower interest rates, more significant borrowing limits, and longer repayment terms but come with the risk of collateral loss. Unsecured loans provide faster approvals, no collateral requirement, and are suitable for businesses with solid credit profiles, but typically come with higher interest rates and shorter repayment terms.
To make an informed decision, evaluate your business’s financial position, collateral availability, risk tolerance, creditworthiness, stability, and specific funding needs. By carefully considering these factors, you can choose the financing option that best aligns with your business’s goals and sets you on the path to success.